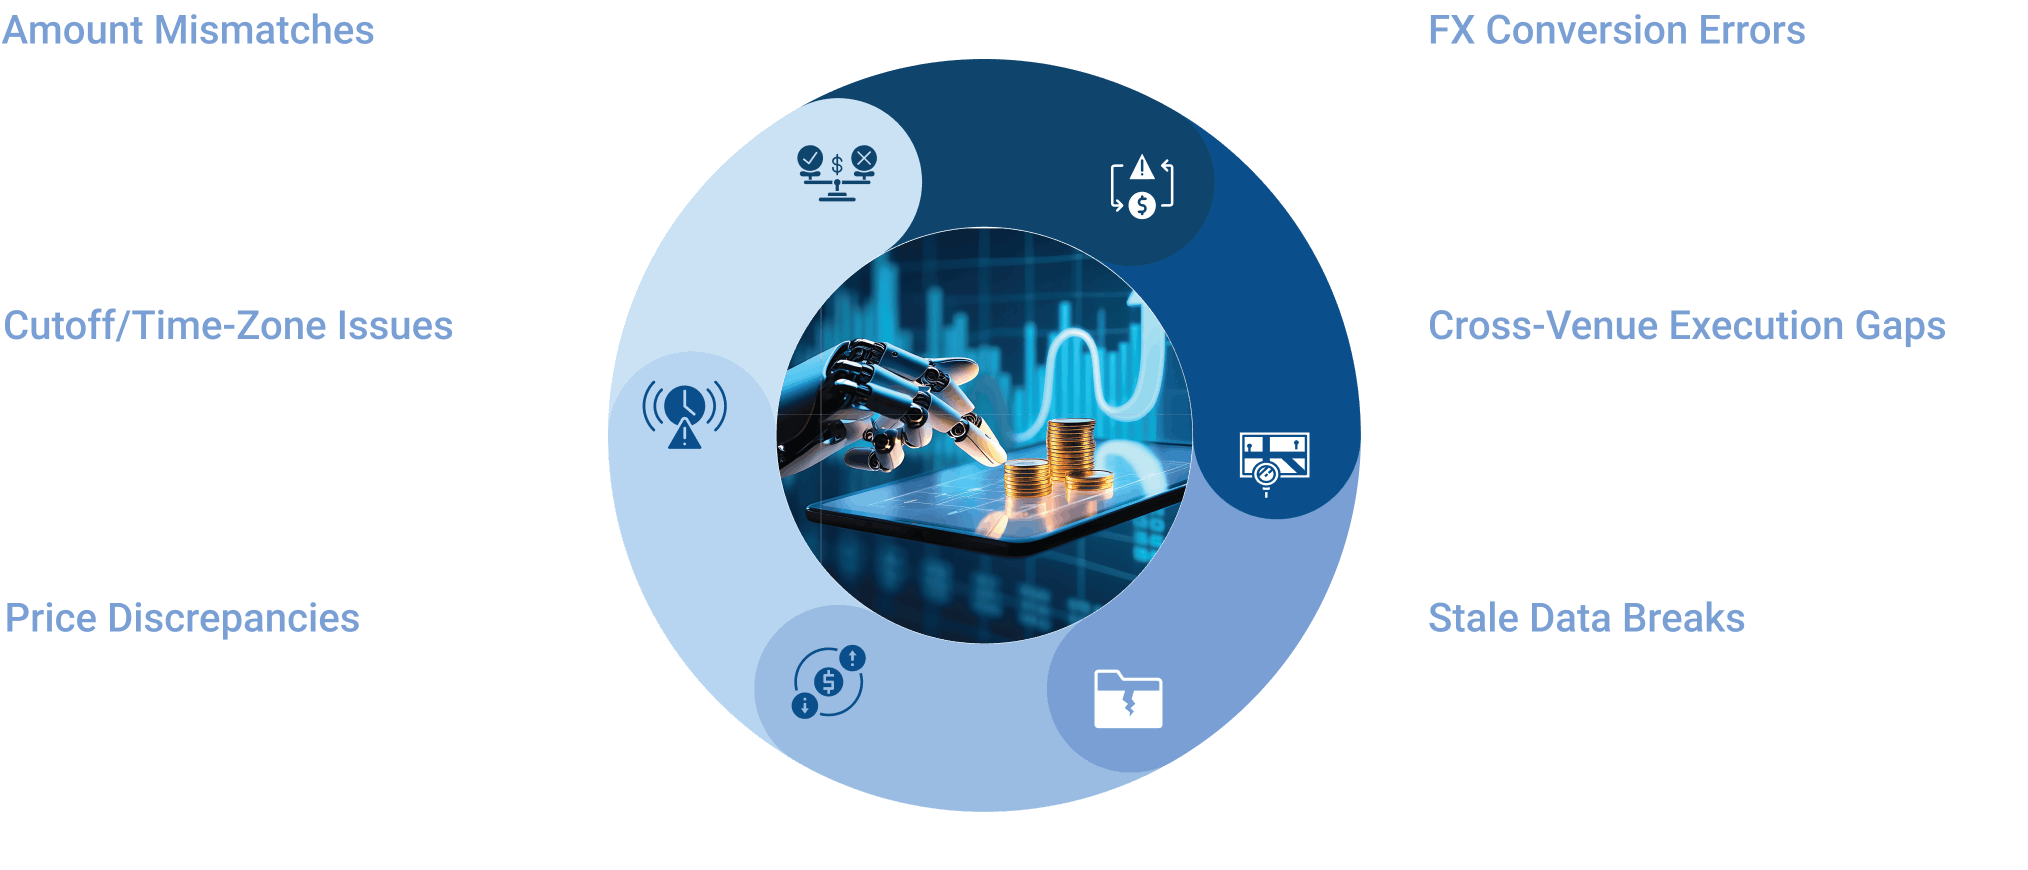
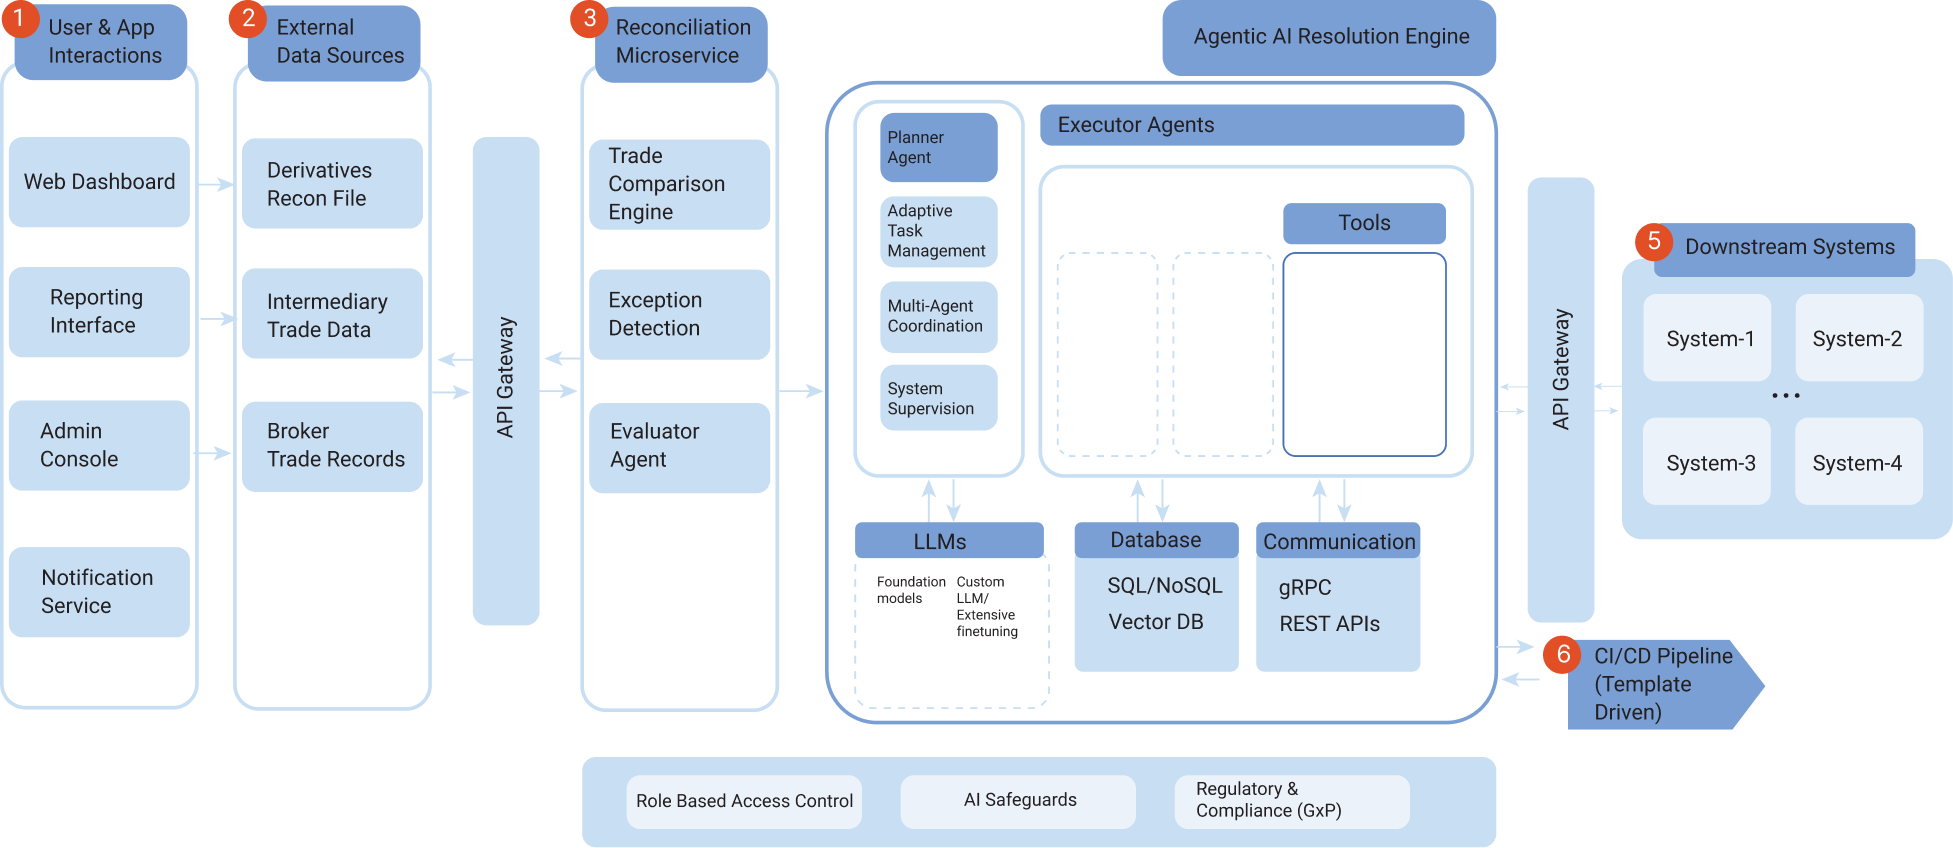
Post-trade reconciliation in global equities and derivatives is a major pain point for large banks. Every day, thousands of trade breaks occur (due to mismatched amounts, cutoff times, pricing errors, FX conversions, etc.), and most are still resolved by hand. These manual workflows are slow, error-prone, and costly: for example, a 2% trade-fail rate (typical in OTC derivatives) can cost the industry about $3 billion per year1. But can LLMs and Generative AI come to the rescue, to automatically reconcile these breaks and save significant manual cost? Simply dumping raw trade data into an LLM is impractical – given that trades of large investment banks run into millions and exception in tens or even hundreds of thousands, the context window and per-token costs would explode, and accuracy demands (~98–99% in trading) are very high2. Instead, agentic AI – i.e. systems of specialized AI agents – can be used to automate reconciliation at scale. This approach combines targeted tools, vector retrieval, and rules-based logic so the heavy lifting is done by smaller agents, not by one brute-force LLM. In this paper we